
WKAP Edition · v1
Liquid-Cooled AI Still Has an Air Bill | 10.19 · $NVT $VRT $ETN
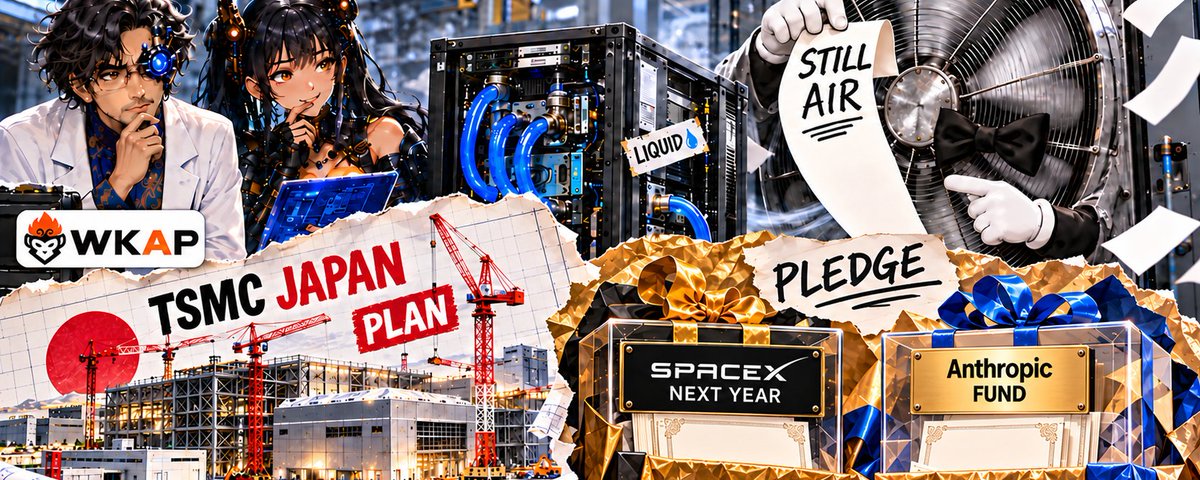
Market take
Liquid-cooled AI racks can still need residual-air equipment, while efficient power architectures can displace other components. The investment test is paid net contribution after bundling, integration and capital cost.
What the market is missing
More physical content and better customer efficiency do not automatically create more supplier margin. Reported cash, acquired revenue, technical capability and future commercial returns belong to different evidence categories.
01 Market Setup
Last week's nVent–AMD announcement contains an easily missed detail: a liquid-cooled AI rack still needs equipment to remove the heat left behind. The new rear-door exchanger is designed to handle that residual load, not replace electricity with water.
That changes the investor question. Instead of buying every “AI power shortage” beneficiary together, ask which supplier gains profitable content as the architecture changes—and which must spend or buy its way into the new bill. nVent supplies the specific cooling example, Vertiv the existing cash-generating system integrator, and Eaton the power-conversion and acquisition comparison.
02 Today’s Trading Map
Follow the physical chain: electricity reaches the facility, conversion and protection deliver usable power, chips consume it, and cooling removes the resulting heat. Better efficiency at one stage can reduce that stage's equipment requirement while increasing useful capacity elsewhere. It does not award every supplier the same earnings growth.
NVT — new rack attachment → qualification, paid shipments and acquisition returns → October 30 results and actual customer disclosures.
VRT — system integration → delivered projects, margins and collected cash → October 28 results.
ETN — fewer conversion stages and broader thermal capabilities → organic growth versus acquired revenue and investment cost → next filed results and deployment evidence.
This is a research queue, not expected returns. The latest financial anchors below are June quarters, not new October earnings. On financial X, power availability, cooling density and project commitments are competing explanations; none alone measures what these three shareholders earn.
03 $NVT — Liquid cooling can leave another invoice
nVent's October 13 release describes a DC-powered, dual rear-door heat exchanger for AMD Helios. It captures heat left by direct-to-chip liquid cooling and returns cooled air to the room. The company describes the intended rack as effectively room-neutral; that does not mean the rack consumes no power or rejects no heat.
The useful mechanism is complementary equipment, not “air versus liquid.” A chip's cold plate and the equipment handling residual rack heat can coexist. But a first-look collaboration is not a disclosed paid installation count, attach rate or project margin. Those missing commercial quantities determine how much of the engineering opportunity reaches earnings. A bundled platform could include the exchanger in one system price: an extra physical part does not prove an extra margin dollar.
Independent researcher @PhotonCap identifies this complementary cooling chain. The author's suggestion that integration could ease operators' total ownership costs is a hypothesis, not a quantified customer saving.
https://x.com/PhotonCap/status/2110956877848977562
There is already genuine business evidence. July's filed results show US$1.471 billion of Q2 sales, 47% organic growth, US$189 million of operating cash and US$167 million of free cash flow under nVent's definition. These are continuing-operations totals, not the Helios product's economics.
Capital allocation complicates the opportunity. October 1's Maverick Power closing cost US$1.75 billion, subject to adjustments, with up to US$550 million of additional performance-based consideration. Buying more power-distribution content also creates an investment that must earn its cost; operating free cash flow is not cash after acquisitions.
Posture: investigate paid attachment and acquisition payback. Confirm with qualified shipments, identifiable commercial contribution and cash returns after integration. Repeated demonstrations without paid adoption leave the case pending. Qualification failure or persistently uneconomic deployments would weaken it. October 30's report can update group economics, but cannot manufacture a product-level disclosure.
04 $VRT — Integration already produces cash
Vertiv supplies the counterexample to treating infrastructure suppliers as promises without earnings. Its July 29 filing reported US$3.274 billion of Q2 sales, including 18% organic growth, and a 22.6% adjusted operating margin.
The cash bridge is explicit: US$1,099.8 million of operating cash less US$173.3 million of capex and US$1.2 million of capitalized software equals US$925.3 million of adjusted free cash flow. Working-capital efficiency and lower cash interest helped. Strong cash is real; that quarter is not automatically a permanent cash-conversion rate.
The new architecture does not have to eliminate Vertiv's role. Its October power-program material explicitly discusses where 800 VDC is appropriate and where AC remains practical. Coordination across power, cooling and commissioning can remain valuable even when particular conversion stages disappear. A program description, however, establishes the proposed engineering scope—not delivered revenue.
Independent research account @ChokepointRes emphasizes the second infrastructure invoice accompanying dense compute. That framing is useful. Its air-only framing does not establish that residual-air equipment disappears. Its backlog characterization, acquisition claims and full-year forecast are not substitutes for current filings; the financial hurdles used here come from the issuer.
https://x.com/ChokepointRes/status/2111820869848781009
Posture: test integration economics at October 28 results. July guided Q3 sales to US$3.650–3.850 billion and adjusted operating margin to 24–25%. Confirm with delivered growth, margin and an explained cash bridge. Joint sales-and-margin shortfalls, or project delays accompanied by worsening collections, would weaken execution. Efficient deployment is the strongest counterargument to blanket infrastructure pessimism.
05 $ETN — Fewer stages do not guarantee more supplier profit
Infineon's September 29 announcement identifies silicon-carbide devices for Eaton's medium-voltage solid-state transformer platform targeting 800 VDC data centers in APAC. The stated aim is fewer conversion stages with better efficiency and density. It is not new electricity generation, nor a disclosed order value or installation timetable.
Independent researcher @Simne1core connects this component-to-system chain and highlights missing commercial terms. That is the useful question. Broader substrate-scarcity and financing assertions in the thread require separate evidence and are not adopted here.
https://x.com/Simne1core/status/2112100270448517563
Eaton already shows why the growth denominator matters. Its Q2 release reports Electrical Global sales up 44%: 18 percentage points organic growth, 25 from Boyd Thermal and one from currency. A larger thermal portfolio is real, but acquired sales are not proof of equivalent organic acceleration. That segment's 19.8% operating margin is also not Electrical Americas' 27.5%.
The investment test is net content: margin from new equipment and services, less margin lost on displaced products, integration costs and the capital required. This is our analytical framework, not Eaton's quantified forecast. Better customer efficiency can support more deployments while competition passes part of the saving to customers.
Posture: separate technical progress from profitable commercial adoption. Confirm through actual deliveries and organic profit/cash after investment, not partnership count. Losing legacy content without adequate replacement earnings would weaken the supplier-benefit thesis. Until commercial terms appear, an architecture announcement alone cannot establish the size of the profit pool.
06 Thematic Read-Through
These businesses can all benefit without earning identical returns. nVent's residual-heat attachment, Vertiv's integrated delivery and Eaton's conversion portfolio face different commercial and capital hurdles.
Pricing already requires earnings, not just recognition. Monday's pre-U.S.-open snapshots were NVT US$142.03, VRT US$206.42 and ETN US$391.25, with latest trade times between 08:19 and 08:54 UTC. Dividing those prices by the midpoints of their respective July full-year adjusted-EPS guides gives approximately 28.1, 30.8 and 29.0 times. These are dated-guide scenarios, not current consensus or interchangeable accounting measures; nVent's guide predates Maverick's closing.
At an unchanged multiple, a 10% earnings shortfall implies a 10% price decline. If earnings and the multiple both fall 10%, the combined decline is 19%. That is arithmetic, not a forecast or downside floor. The profitable-content bridge has to justify the price before a compelling technology story becomes an attractive stock.
Source 1 · Source 2 · Source 3 · Source 4 · Source 5 · Source 6
07 WKAP 30/30 List
WKAP's 30/30 means potential for a 30% gain within 30 calendar days. None qualifies on today's evidence: no supported hurdle, dated catalyst, downside and probability case establishes that opportunity.
Keep NVT's paid attachment, VRT's execution and ETN's net-content return as research candidates. Promotion requires an exact baseline, hurdle and deadline, plus separate probabilities for an intraday touch, a qualifying close and holding the level. A more complicated rack can create another invoice; only commercial economics determines who keeps it.
What to watch next
- NVT: October30 results and qualified paid-deployment disclosures; identify pricing/attach rate/contribution and Maverick capital returns where disclosed.
- VRT: October28 actual sales/margin/cash versus the original July guide; explain collections, working capital and interest rather than annualize one quarter.
- ETN: next actual filing/deployment disclosure; reconcile organic/acquired/FX growth, displaced profit and investment cost. Report date not asserted.
What would invalidate this take
- NVT: qualification failure or persistently uneconomic deployments weaken the commercial extension; demonstrations or missing disclosure alone leave it pending.
- VRT: joint sales/margin shortfalls or project delays with worsening collections weaken execution; sustained inadequate integrated capital returns invalidate resilience, not historical cash.
- ETN: lost legacy contribution without replacement earnings weakens net content; persistently adverse net capital economics invalidate automatic supplier-benefit claims, not customer efficiency.
Creative brief
Episode premise
WKAP watches a daily market collision: a liquid-cooled rack still has an air bill, Japan fab plans require future execution, and highly visible equity gifts remain conditional or future pledges.
Market hooks
nVent's Helios design handles residual heat alongside direct-to-chip liquid cooling.
Complementary equipment can remain, but paid attachment and extra margin are not established by the technical announcement.
TSMC's Japan account described the second JASM fab's advanced-node plan, phased with demand and government support.
Geographic AI capacity investment has a construction and qualification clock; a plan is not current operating output.
Anthropic announced an equity commitment to a public-benefit fund, while Musk pledged future SpaceX shares for American children.
These high-attention statements concern ownership and distribution, not completed public transfers. Anthropic's initial commitment is subject to stockholder approval; Musk said next year.
Scene development
Liquid cooling still leaves a residual-air role.
- Visual joke
- An absurdly oversized formal fan arrives with an endless STILL AIR bill while the market wraps promises like gifts.
- Characters
- Only approved 院长 and Alice as watchers; photographic rack/fan and paper bill.
- Why they belong
- The physical equipment earns its place through the specific residual-load design. The anchors observe the mismatch between a technology story and its economic bill, not act as customers or funders.
- Relationship semantics
- Complementary cooling, not a corporate rivalry. The bill is economic satire, not a real invoice, paid-unit count or extra-margin disclosure.
- Action
- The bow-tied fan points at its bill beside the closed-loop rack; both anchors watch with dry skepticism.
Japan advanced-fab plans are future capacity commitments.
- Visual joke
- An oversized torn PLAN sheet brings a construction scene into the industrial/newsroom collision.
- Characters
- Photo-style construction/crane and a distinct paper blueprint, no added mascot or market-person likeness.
- Why they belong
- The current issuer statement justifies a prominent geographic-capacity story outside the Article's three stocks. The plan label preserves its forward-looking status.
- Relationship semantics
- A conceptual construction image, not a documentary photo of an operating new JASM fab or guaranteed return; no funding link to the other stories.
- Action
- The construction plan protrudes as a separate source island while the anchors survey the whole panorama.
Equity commitments are not completed gifts.
- Visual joke
- Two dramatically overwrapped but closed share-paper cases promise gifts beside an immediate-looking air bill.
- Characters
- Separate SpaceX/NEXT YEAR and Anthropic/FUND paper displays under PLEDGE; no invented recipient or additional character.
- Why they belong
- The named current statements and observed attention earn the displays, unlike generic meme recognition. Distinct cases retain different governance and timing.
- Relationship semantics
- Future or conditional commitments only; not a joint fund, completed share transfer, cash distribution, financial valuation or partnership with TSMC or the rack supplier.
- Action
- The two closed pledged-share displays remain adjacent but separated, with names and timing labels inside the saved crop-safe band.
Credits
- Human
- Alex set purpose, cast and taste and directed the no-default-mascot, daily-market-panorama and separate-review correction. No final daily image approval is claimed.
- AI
- Codex researched and wrote the analysis and generated the cover with ImageGen. A separate coordinating reviewer critiqued v6, followed by producer verification of the saved X crop and phone conformance.
- Publisher
- WKAP / @memely
Rejected choices
- An unrelated generic meme mascot was excluded; recognition alone did not earn a current-market role.
- Unverified brokerage/order-cancellation and custom-HBM claims were omitted in favor of primary-statement hooks.
Corrections
- The cover remit broadened beyond the Article's three stocks while preserving the serious investment thesis.
- Pledge labels were moved into the crop-safe band; the actual saved X rendition retained them at phone width after independent review and conformance checks.
Lesson for the next edition
Earn every cameo and prop with a current source-backed role. Inspect the actual hero, saved crop and phone rendition, and obtain a separate critical editorial review rather than treating a creator score as approval.
Daily Market Meme Challenge
Roast our take, spot an egg, or show us your market meme. Tell us what today's market is missing.
These hashes and OpenTimestamps evidence bind the exact published journal and cover bytes. They do not prove authorship, invention, or the exact time the creative work was made.