
WKAP Edition · v1
AI Storage Is Growing. How Much Profit Depends on Price? | 10.23 · $WDC $STX $SNDK
Market take
AI storage demand is real, but physical capacity, retained price/mix and sustainable shareholder earnings are different variables.
What the market is missing
WDC revenue grew much faster than shipped exabytes. That blended monetization contribution is not matched-product ASP or a permanent margin floor. HDD density benefits and NAND contract coverage need separate profit, cash and duration tests.
Market Setup
For Friday, October 23, 2026: Western Digital's new results show real storage growth: revenue rose 55% from a year earlier, while shipped capacity increased about 22%. The gap matters. AI can create more data to store without guaranteeing that today's revenue per unit of capacity—or today's profit margin—lasts indefinitely.
The investor question is not simply whether storage demand is strong. It is how much earning power comes from more capacity, how much from pricing and product mix, and who retains the benefit of better technology. WDC provides the fresh operating test; Seagate provides next week's hard-drive comparison; Sandisk supplies a different business model in NAND flash. Buying all three as one “AI memory” trade skips the important distinctions.
Today's Trading Map
Hard drives and flash serve different cost, capacity and performance requirements. More valuable retained data can expand the opportunity for both; it does not make every stored byte equally profitable. WDC and Seagate sell hard drives. Sandisk, separated from WDC in 2025, sells flash. Do not count the former combined company as one current operating exposure.
Follow three variables: capacity delivered, revenue retained per unit of capacity, and the cost of producing it. Then ask what contractual protection survives the next supply response. Research priority is WDC's fresh price/mix bridge, Seagate's October 27 execution test, then Sandisk's October 29 pricing-duration test. That is a work queue, not an expected-return ranking. The peer financial results below are older July-ended quarters, not three overnight earnings releases.
$WDC — Capacity growth explains only part of the sales growth
The current earnings presentation shows fiscal-Q1 shipped capacity rising from 204 to 248 exabytes, while revenue rose from $2.818 billion to $4.381 billion. Dividing revenue by total capacity implies roughly 28% higher blended revenue per exabyte. That is our calculation, not a matched-product price increase: product mix and the scope of the revenue numerator matter.
This changes the monitoring task. A model that extrapolates the 55% sales growth as physical demand alone is implicitly carrying forward a substantial price/mix contribution. More capacity can keep growing even if that contribution moderates. Conversely, a move toward more valuable products can support revenue without proportionate growth in drive units.
The October 22 financial tables show genuine retained economics: 57.8% GAAP gross margin, $1.604 billion of operating cash and $1.377 billion of free cash flow after $227 million of net property purchases. Management's next-quarter outlook is $5.0–5.2 billion of revenue and 60–61% non-GAAP gross margin. Those are forecasts, not a permanently achieved margin floor.
Independent, AI-assisted research account 株浪漫 makes a useful distinction between storage capacity and drive counts. Its bio discloses generative-AI research and writing; this is a research voice, not verified human analyst expertise. Its call-attributed cost, capex and supplier-order claims require their original sources and are not adopted here. Its explanation for the stock reaction is also interpretation, not proven causality.
Posture: investigate durability, not deny the strong quarter. Confirmation requires delivered growth and cash with an explained volume/price/mix bridge. Revenue below $5.0 billion together with adjusted gross margin below 60%, without a quantified timing explanation, would weaken near-term execution. Persistent customer price concessions outrunning cost improvements would challenge the longer-duration profit case even if exabytes keep rising.
$STX — Better density must earn more than customer savings
Seagate's July 29 report already demonstrated substantial cash generation: $3.629 billion of quarterly revenue, 52.3% GAAP gross margin and approximately $1.1 billion of free cash flow. The quarter ended July 3. July's next-quarter guide was $4.0–4.2 billion of revenue and $7.10–7.50 of non-GAAP EPS; it is not a fresh October reaffirmation.
Its Mozaic/HAMR roadmap addresses mass-capacity storage. The economic attraction is higher useful capacity from the production platform. But lower cost per bit is not automatically retained supplier profit: yields, product mix, customer pricing and investment decide how the benefit is divided. Technical progress can be excellent for customers while producing less shareholder upside than a simple shipment-growth story suggests.
Independent researcher 456X connects HAMR adoption and customer commitments to stronger earnings expectations. The useful question is whether density improvements become paid, profitable output. Its unnamed analyst forecasts, projected shipment growth, spot-price multiples and industry shortage estimates are not reported Seagate results. A preview written in the present tense must not become our historical fact.
Posture: use October 27 results to separate volume, mix and cost execution. Confirmation means guide delivery and an explained profit-to-cash bridge as new products scale. Customer pushouts, weaker manufacturing economics or results below the old revenue and EPS floors would challenge execution. WDC's strong report raises the relevance of the comparison; it does not pre-report Seagate's quarter.
$SNDK — Contracts can extend visibility without abolishing the cycle
Sandisk's August 5 results make the pricing dependency unusually explicit. July-ended quarterly revenue rose 51% sequentially; management attributed approximately one-third of that growth to volume and two-thirds to pricing. That is a decomposition of growth, not a claim that two-thirds of all sales was price. Datacenter revenue was $2.977 billion of $8.965 billion total, so this is not a pure AI-inference revenue stream.
The commercial counterargument deserves attention. At August's Investor Day, Sandisk described eight customers under New Business Model agreements, covering approximately half of fiscal-2027 bits and two-thirds of fiscal-2028 bits. Committed volumes, minimum financial guarantees and structured pricing can improve planning. Bit coverage is not revenue coverage, and these descriptions do not guarantee today's margin through every future demand shock.
The cash is substantial, too. July's reported free cash flow was $7.083 billion. Sandisk then deducted $110 million of net Flash Ventures activity and $1.938 billion of NBM prepayments and deposits to report $5.035 billion of adjusted free cash flow. That preserves real cash strength while separating advance funding and joint-venture investment; it is not the same definition as WDC's simple operating-cash-minus-property-purchases measure.
Independent investor Marcel Larsen supplies the important bullish objection: supply-chain demand evidence can improve while memory-stock multiples compress. His forward multiples, contracted-revenue figure and attributed estimate revisions are not reconciled to primary definitions in the post. We retain the argument, not those unsourced valuation inputs. A lower multiple can reflect excessive fear—or earnings that investors expect to normalize.
Posture: test price duration and contract economics at the October 29 report. August guided quarterly revenue to $10.3–10.8 billion and non-GAAP EPS to $44–46. Confirmation requires delivered pricing/volume and useful protection when contract terms reset. Weaker realized pricing with deteriorating profitability or reduced customer protection would weaken durability. A favorable technology roadmap or enormous backlog-like number cannot answer those questions alone.
Thematic Read-Through
The valuation trap is annualizing a strong quarter and calling the smallest multiple the best opportunity. October 23 premarket observations were WDC $354.19, Seagate $642.14 and Sandisk $1,260.93, with latest trade timestamps between 08:56 and 08:59 UTC. Dividing by four times each company's latest quarterly adjusted-EPS guide midpoint gives roughly 15.3, 22.0 and 7.0 times, respectively.
These are transparent guide-run-rate sensitivities, not consensus forward P/Es, normalized annual earnings or comparable fiscal periods. Sandisk's lower number places more weight on how much current pricing survives. At a constant price, a 25% earnings reduction raises any such multiple by one-third. If earnings and the valuation multiple both fall 25%, price falls 43.75%: arithmetic, not a forecast or downside floor.
The strongest countercase is durable demand plus disciplined supply and effective customer contracts. Today's results do not disprove it. They identify what must persist before impressive technology and growing data justify the stock price.
WKAP 30/30 List
No new qualified entry. WKAP's 30/30 means potential for at least 30% within 30 calendar days, supported by a dated catalyst, downside framework and separate intraday-touch, qualifying-close and hold probabilities. Neither a sharp drawdown nor a low annualized-quarter multiple supplies that case.
Keep WDC's price/mix retention, Seagate's density-to-profit conversion and Sandisk's contract-protected pricing in research. Promote only when sustainable per-share earnings and a defensible price-based upside/downside model earn inclusion. More stored data is the opportunity; retained economics and the price paid determine the investment.
What to watch next
- WDC original capacity/price/mix/cost bridge and delivery against its new revenue and adjusted-margin ranges.
- Seagate October 27 actual revenue, diluted earnings, paid density progress and cash against July guidance.
- Sandisk October 29 price/volume, contract protections and cash after venture and NBM adjustments.
What would invalidate this take
- Persistent WDC customer concessions or production costs defeat retained monetization despite rising capacity.
- Seagate customer pushouts or uneconomic manufacturing prevent density progress becoming paid profit.
- Sandisk realized-price deterioration plus weaker profitability/cash, or evidenced erosion of customer protection, challenges pricing durability.
Creative brief
Episode premise
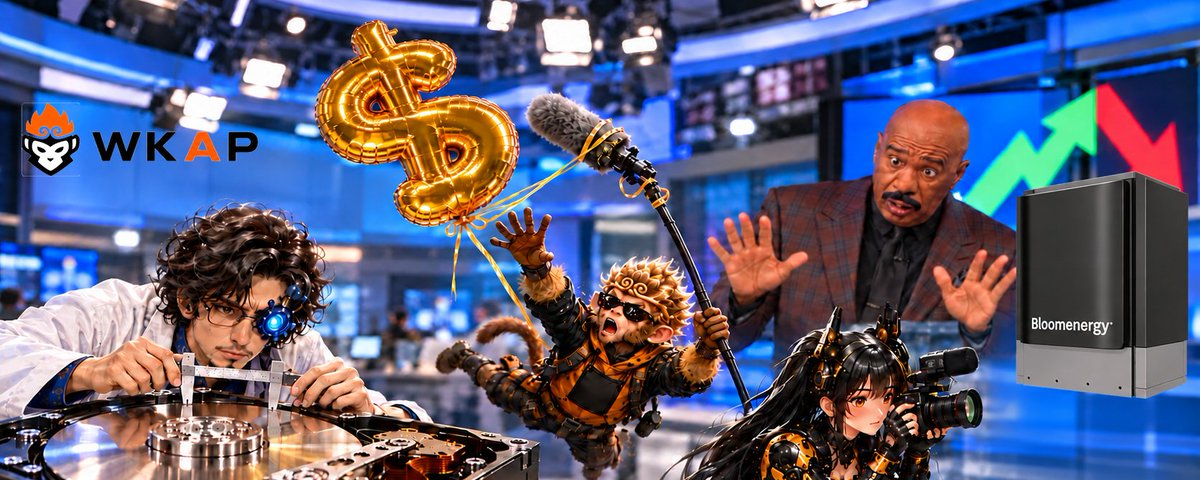
WKAP measures physical storage while an oversized dollar balloon tangles the reporting equipment; a separate Bloom product cutout and current television-reaction meme interrupt the earnings celebration.
Market hooks
WDC reported much faster revenue than exabyte growth, alongside strong margin and cash.
Physical demand and retained blended monetization need separate durability tests; the proxy does not establish matched-product pricing.
Bloom reported record quarterly revenue and operating profit while working-capital uses left operating cash negative.
A strong reported result and genuine AI-power opportunity do not remove collection timing or valuation questions. This is not a fraud, default or failed-power claim.
A current reply to Bloom results used a Steve Harvey double-take clip to question whether good results help the stock.
The directly inspected reaction earns a small photographic cultural counterpoint, not a CEO role, an engineering claim or a proven explanation of the share move.
Scene development
The blue-monocled human tests a giant hard drive while the monkey boom operator becomes caught in a swollen dollar-balloon string.
- Visual joke
- The journalist trying to measure the hardware has to contend with a price balloon large enough to entangle the reporting equipment.
- Characters
- Approved human 院长 with blue cyber-monocle and golden WuKong AP monkey in sunglasses; hard-drive and dollar-balloon personification.
- Why they belong
- The anchors investigate storage economics, not invest in the companies. The balloon distinguishes a swollen monetization contribution from the physical drive.
- Relationship semantics
- Satire of separate capacity and blended monetization drivers, not exact matched-product pricing, issuer misconduct or a contractual relationship.
- Action
- Human uses calipers; airborne monkey tries to manage a boom tangled in the balloon string.
Alice records an authentic black-and-gray Bloom product-render cutout beside the photographic Steve Harvey reaction earned by the current earnings conversation.
- Visual joke
- A native television double-take interrupts the storage reporters' physical slapstick and the strong-results celebration, echoing the actual reply's good-for-the-stock question.
- Characters
- Approved Alice with long dark hair and black-and-gold headgear; recognizable Bloom platform geometry and the actually inspected current Steve Harvey reaction frame.
- Why they belong
- Alice documents rather than buys power. Current Bloom earnings earn the subordinate product hook; the directly inspected reply earns Steve, not generic celebrity recognition.
- Relationship semantics
- Separate product-render and photographic realities form a collage, not levitating engineering, issuer failure, an alliance or Steve acting as an officer/customer. The visual does not claim to depict working-capital accounts.
- Action
- Alice actively aims the camera toward the full product cutout and open-palmed reaction; the secondary collision stays subordinate to the entangled boom and measuring action.
Credits
- Human
- Alex set WKAP purpose, approved cast and creative direction; no daily human approval is claimed.
- AI
- AI researched and drafted the full analysis, generated the cover from inspected identity and source references, and composed the exact official WKAP asset. A separate authorized AI reviewer inspected local, saved-X and genuine phone evidence.
- Publisher
- WKAP / Memely Alpha (@memely).
Rejected choices
- A Griffin portrait lost prominence because original full-interview context was unresolved and the funding motif repeated recent episodes.
- High-attention political, fund-blowup and model-odds posts did not earn space without resolved facts and a useful current market relationship.
- Static green earnings cards, default Pepe and the old flying-car joke were not substituted for current comic action.
Corrections
- The Article added Sandisk’s explicit reported-to-adjusted free-cash-flow reconciliation to retain genuine cash strength without confusing definitions.
- Private repairs corrected the canvas and composed the actual official mark, removed a misleading printer/invoice metaphor, and retained the complete authentic Bloom product cutout in the crop.
- Radar result tests now classify each reported measure separately before any mixed-result or durability verdict.
Lesson for the next edition
Check truthful product semantics and complete secondary hooks in the intended crop early, while keeping the wordless main action dominant. Judge practical phone usability without inventing a requirement that every secondary brand word be readable.
Daily Market Meme Challenge
Roast our take, spot an egg, or show us your market meme. Tell us what today's market is missing.
These hashes and OpenTimestamps evidence bind the exact published journal and cover bytes. They do not prove authorship, invention, or the exact time the creative work was made.